mortgage broker Coombabah
Welcome to the Coombabah home loan experts.
We've been helping Coombabah home buyers, investors and families since 2011, with home loan advice that works for you - not the bank.
About Serres, mortgage broker Coombabah
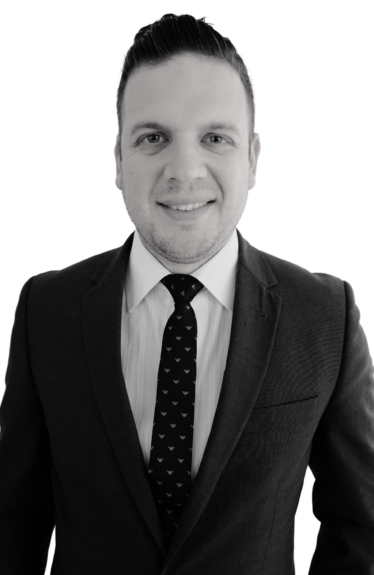
Meet Lee Tsiboukas, Senior Mortgage Broker helping Coombabah locals.
For over 15 years Lee has run a private REIT with a diverse property portfolio — the foundation of Serres Property Finance. The business came out of something he kept noticing: lending is constantly evolving, and so are clients' needs.
There was a time when your bank manager knew you, and trust and service mattered more than a credit file. Then the GFC hit, the Banking Royal Commission followed, and the doors got harder to open — especially for complex borrowers like the self-employed, investors and first home buyers. Now, knowing which lender to approach and what they'll actually say yes to makes all the difference.
Lee's family are property owners and investors themselves. They started with one investment property in Newtown, then moved into care facilities and multi-storey residential development. So whether you're buying your first home, building toward retirement, or running a development, Lee knows the challenges you face and how to get the right outcome.
Credit Representative 550725 is authorised under Australian Credit Licence 486112.
1. Schedule a free chat.
Coombabah is a large, affordable northern suburb of houses, over-50s communities and bushland beside the Coombabah wetlands. Send Lee the address and you'll know what fits before you make an offer. Same broker every time, start to finish.
2. We find better loan options.
Over-50s and lifestyle-community titles, site-fee arrangements and older homes all change how a lender assesses a Coombabah property. We explain what applies in plain English. Buying your first? See first home loans.
3. Get approved.
With 70+ lenders we place your file where it fits and negotiate from there. Retired or self-funded? We assess that income properly, where many banks won't. Clients who refinanced with us last year saved an average of $487 a month. See refinancing.
Coombabah HOme Loan Experts
We make even the most complex Coombabah home loans simpler.
Buying, building, investing or refinancing, we can help.
Pre-Approvals
Secure your dream Coombabah home with confidence. Get pre-approved for a mortgage and be ready to make an offer when the perfect opportunity arises.
Home Loans
Navigating the home-buying process can be overwhelming. Let us guide you every step of the way, ensuring a smooth journey to becoming a proud homeowner.
Home Loan Refinancing
Save money on your monthly mortgage repayments. Our Coombabah mortgage broker can help you explore refinancing options that suit your needs.
Self-Employed Mortgages
Being self-employed shouldn’t hinder your dream of owning a home. We specialise in finding solutions for entrepreneurs, making it easier to qualify for a loan.
Investment Property Loans
Expand your Coombabah or Australia wide real estate portfolio with ease. Our tailored investment property loan solutions can help you maximise your returns.
Specialised Debt Structures
Navigate complex financial situations with ease, from reverse mortgages to tailored debt release structures, our experts help you find unique solutions.
How Our Coombabah Mortgage broker helps
How does our mortgage broker help?
Around 70% of Australian home loans now go through a broker, and in an affordable, retiree-weighted suburb like Coombabah that matters more than most. First home purchases, over-50s and lifestyle stock, and retiree income are exactly the files where knowing which of our 70+ lenders will say yes saves you weeks and a string of credit enquiries.
We also review your rate every twelve months for as long as you hold the loan, commission or not, so the loan on your Coombabah home is still the right one in five years. Schedule a call to find out more.
Accredited with 70+ lenders.
We negotiate with over 70 banks & lenders.
Some of the lenders we work with include:
our MORTGAGE BROKER's REViews
“Serres helped with my refinance and did an excellent job finding me the right lender for my circumstances. I was kept up to date and everything moved forward as planned. Couldn't recommend Lee and Serres enough!"
Spica Delorino
June 2026
★★★★★
Contact our Coombabah broker today
Chat to Lee & our local home loan experts today.
Our team have over fifteen years experience helping Gold Coast locals, simply get in touch today.
Get in touch.
I'll reply the same way you contacted me, unless you say otherwise.
Contact Us
FAQs.
Home loans should be simple, transparent and tailored to you. Here are the questions we're asked most often, with no jargon - just straight answers.
How do first home buyers and downsizers get into Coombabah?
Coombabah is a large, relatively affordable northern suburb of houses, over-50s communities and bushland beside the Coombabah Lake wetlands. Its affordability and its lifestyle-community stock make it a common choice for first home buyers, downsizers and retirees, and the property type drives the lending.
Coombabah sits in the 4216 postcode. At the 2021 Census it had 10,298 residents, a median age of 51 and 5,023 private dwellings at an average of 2.1 people per household. Median weekly household income was $1,092, below the Gold Coast median, and home ownership is high, so many local buyers are downsizers or long-term owners.
Deposit and property type
Budget 20% plus costs for the widest lender choice and no Lenders Mortgage Insurance, though 10% and 5% deposits are workable. A standard house is straightforward; an over-50s, lifestyle-community or manufactured-home dwelling is a different matter, funded by only a handful of lenders and sometimes not at all. Start with our borrowing power calculator, then get a real number through pre-approval.
Over-50s and lifestyle communities
Coombabah has several over-50s and lifestyle communities. Age-restricted titles, site-fee arrangements and land-lease structures all affect whether and how a lender will proceed, so we check the specific title before you commit. See downsizing.
First home buyer schemes
Queensland's First Home Concession removes transfer duty on an established home up to $700,000, which covers most Coombabah stock, phasing out to $800,000. The federal First Home Guarantee allows a 5% deposit with no LMI within 2026 price caps. See first home loans. We also help buyers across neighbouring Biggera Waters, Arundel and Runaway Bay.
Call Serres on 1800 040 030 for a free assessment of your Coombabah options.
How does investment lending work in Coombabah?
Coombabah's affordability, family housing and quiet, wetland-fringed setting give it steady tenant demand close to the Broadwater and Harbour Town. Median weekly rent was $415 at the 2021 Census. For lending, the property type is the main variable, since the suburb spans standard houses and lifestyle-community stock.
A standard leased house assesses much like any investment loan: your income, the projected rent, your existing commitments and how the loan sits in your portfolio, with lenders accepting from 80% of the appraised rent upward. The suburb's stable tenant base tends to suit most lender models.
Standard houses versus lifestyle stock
Over-50s, land-lease and manufactured-home dwellings are generally not standard security and are funded by only a few lenders, so they suit owner-occupiers more than investors. We tell you upfront which stock a mainstream investment lender will accept. See our investment loan page.
Dual income and granny flats
Some larger Coombabah blocks suit a secondary dwelling, and lender treatment of that second income varies sharply. Confirm the council position and the lender's income treatment before committing.
Using equity
With high ownership rates locally, releasing equity to fund an investment is common, and how it is structured decides whether your servicing still works. See refinancing and equity release.
Call Serres on 1800 040 030 to talk through Coombabah investment finance.
When does it make sense to refinance or downsize in Coombabah?
Refinancing a Coombabah loan usually makes sense when your fixed rate is ending, you have built equity to fall below 80% LVR, you want to release equity, or your income has changed. With a settled, high-ownership suburb, a lot of local owners are sitting on equity worth reviewing.
Median monthly mortgage repayments in Coombabah were $1,647 at the 2021 Census, lower than the coast average, which reflects the suburb's affordability. Even so, a genuine rate review is often worth more than owners expect.
Your fixed rate is ending
The revert rate a lender rolls you onto is rarely their best offer. Start two to three months before expiry, because a refinance takes weeks.
Releasing equity
If your LVR has fallen below 80% you may avoid LMI on a new loan and release equity for a renovation, an investment deposit or to consolidate higher-interest debt. Consolidating stretches the term, so check the total interest, not just the monthly figure. See debt consolidation and our loan repayment calculator.
Downsizing within the suburb
Many local moves are downsizes into an over-50s or lifestyle community. These purchases are funded by fewer lenders, and buying before selling with bridging finance or a deposit release are options, with retiree income adding its own considerations. See downsizing.
When it is not worth it
If your balance is small or fixed-rate break costs exceed the saving, staying put is the better call, and we will say so.
Call Serres on 1800 040 030 for an honest read on whether refinancing suits you.
Can self-employed, retiree and complex borrowers get a loan in Coombabah?
Yes, and both self-employed and retiree lending are common here. Coombabah has an older profile, with a median age of 51 at the 2021 Census and a strong over-50s presence, so many applications rest on business income, investment income or self-funded retirement income rather than a simple payslip.
What matters is which lender reads that income properly, because policy on non-salary income varies more than most borrowers expect, and a lower median income locally makes the right lender match matter even more.
Business owners and sole traders
Most lenders want two years of company and personal returns and notices of assessment. Add-backs such as depreciation, one-off expenses, additional super and interest on debt being refinanced can lift assessable income, and lenders differ on which they accept. Some use your most recent year alone. See self-employed home loans.
Retiree and self-funded income
Superannuation drawdowns, investment income and part-pension income are assessed favourably by some lenders and conservatively by others, particularly where a loan term runs past retirement age and a lender wants a clear exit strategy. See downsizing and retiree lending.
Casual, alt doc and past credit
Casual and part-time income, alt doc lending on BAS, and applications with a past default are all workable with the right lender rather than a blanket bank checklist. See lending after credit issues.
Call Serres on 1800 040 030 to discuss your situation confidentially.
How do local incomes and households shape lending in Coombabah?
At the 2021 Census Coombabah had 10,298 residents with a median age of 51, living at an average of 2.1 people per household across 5,023 dwellings. Median weekly household income was $1,092, median weekly rent was $415 and median monthly mortgage repayments were $1,647.
An affordable, older suburb
Small households, a mature median age, a lower median income and high home ownership mark Coombabah as an affordable, settled suburb with a strong retiree and over-50s presence, balanced by first home buyers. In practice that means a mix of retiree, first home and downsizer applications, where lender treatment of non-salary income and of lifestyle-community stock is decisive.
Houses and lifestyle communities
Standard houses and over-50s, land-lease and manufactured-home communities sit side by side in the suburb, and they are funded very differently. Age-restricted and land-lease titles are the single biggest thing that changes which lenders will proceed.
What this means for your application
For a Coombabah purchase or refinance, matching your income type and the specific title to the right lender is the biggest single variable in the outcome. See home loans.
Where Serres fits
We are Gold Coast based and compare more than 70 lenders, matching your income structure and the specific property to the lender most likely to assess it favourably. Serres Finance Pty Ltd trading as Serres Property Finance, Credit Representative 550725, authorised under Australian Credit Licence 486112.
Source: Australian Bureau of Statistics, 2021 Census of Population and Housing, Coombabah (SAL30687).
Call Serres on 1800 040 030 for a free assessment of your borrowing position.